The National Pension Commission has introduced an automated system for calculating penalties against employers who delay remitting workers’ pension contributions, as part of efforts to strengthen compliance with the Pension Reform Act.
The commission said employers with outstanding penalties cannot obtain Pension Clearance Certificates until they settle their liabilities, which could affect their eligibility for government contracts and other business transactions that require evidence of pension compliance.
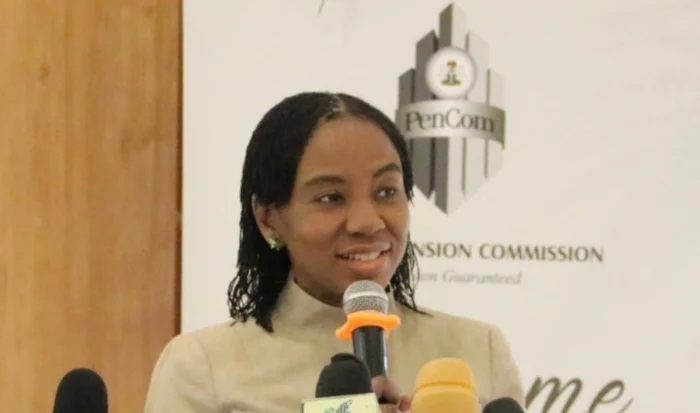
The Director-General of PenCom, Omolola Oloworaran, disclosed this on Tuesday during the 2026 Annual PenCom Media Conference in Abuja.
“I would also note that the new system we just implemented for PCC auto-calculates penalties. So, if you are requesting a pension plan certificate, and there are any delays in you remitting your pension until you pay your penalties, you will not be able to get your pension plan certificate,” she said.
Oloworaran explained that the initiative was designed to ensure that employers fulfilled their obligations to workers under the Contributory Pension Scheme.
Although penalties for delayed remittances already exist under the pension law, the automated system links the calculation and settlement of outstanding penalties to the issuance of clearance certificates.
She acknowledged that some employers continued to withhold contributions or delay payments despite regulatory interventions.
“But we are monitoring, and we are going after employers who are not contributing and also those who are not contributing in time as well,” she said.
The DG disclosed that PenCom had extended pension compliance requirements to commercial relationships involving pension operators and their business partners.
She cited First Bank, United Bank for Africa, Guaranty Trust Bank, Access Bank and Zenith Bank as examples of major financial institutions with pension industry affiliations that could support the enforcement measures.
According to her, pension fund operators are also prohibited from investing in companies that fail to remit pension contributions for their employees.
She explained that the restrictions covered investment placements and other financial transactions involving non-compliant organisations.
Oloworaran said the commission had engaged recovery agents to examine employers’ records, determine outstanding pension liabilities and facilitate the recovery of unpaid contributions.
She disclosed that cumulative recoveries from defaulting employers had reached N36.6bn as of July 2026, adding that recoveries recorded during the year had already surpassed the previous annual record.
“A deduction on a payslip that does not reach a Retirement Savings Account is a breach of trust and a breach of the law,” she declared.
“We will find what is owed, we will recover it, and we will hold those responsible to account.”
On compliance by state governments, Oloworaran disclosed that two additional states had commenced pension contributions in 2026, although they had yet to meet all the requirements for full implementation of the scheme.
She said PenCom was engaging state governments to improve compliance and strengthen retirement benefits for their workers.
The DG also disclosed that the commission had introduced quarterly engagements with the Integrated Personnel and Payroll Information System to resolve cases of pension deductions that had not been remitted to workers’ retirement savings accounts.
She maintained that delays in processing retirement benefits had been substantially addressed, with Pension Fund Administrators now required to approve benefit requests within 48 hours, compared with delays of up to 21 months previously.
Oloworaran said PenCom had transferred routine benefit approval responsibilities to PFAs to eliminate administrative bottlenecks and concentrate on regulatory oversight.
She added that the commission expected complaints to receive responses within 24 hours, or 48 hours where additional time was required.
Beyond enforcement, the DG disclosed that pension assets increased from N20.79tn in July 2024 to N31.48tn in June 2026, representing a rise of N10.69tn, while 938,229 additional Nigerians joined the Contributory Pension Scheme during the period.
She also said the Federal Government’s N758bn pension bond intervention had benefited 957,045 people, with the funds substantially disbursed.
According to her, Pension Boost 1.0 increased monthly payments to more than 241,000 retirees, raising aggregate monthly pensions from N12.15bn to N14.83bn.
Speaking on behalf of Pension Fund Administrators, the Managing Director and Chief Executive Officer of Access ARM Pensions, Sa’adu Jijji, commended PenCom for introducing reforms aimed at improving the administration of retirement benefits.
Jijji pledged pension operators’ commitment to implementing the commission’s initiatives and ensuring the changes translate into improved services for contributors and retirees.
In a goodwill message, the President of the Pension Correspondents Association of Nigeria, Nana Musa, called for greater professionalism and deeper understanding of pension issues among journalists covering the industry.
Musa, represented by the association’s Treasurer, Oluwakemi Kindness, said accurate, balanced reporting is necessary to help Nigerians understand pension policies, retirement entitlements, and regulatory developments.